
Macroeconomic Policy Must Pave the Way for Development and Reflect the People’s Demand for Change

National Executive Committee of the PCdoB
Date: November 15, 2026
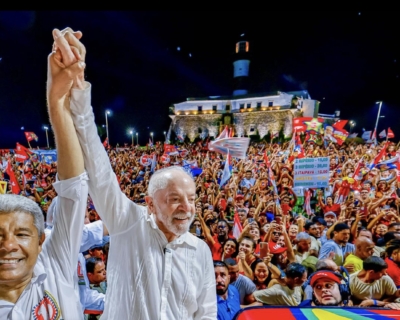
The historic re-election of President Lula, carried forward by gigantic popular demonstrations in the streets and on social media, defeated an explicit fiscal adjustment agenda — the so-called “tesouraço bolsonarista” (the Bolsonarist budget axe) — and sent a clear message about the need for a change of course in the macroeconomic policy that has increased the indebtedness of families and businesses, reduced growth and strangled social mobility. Yet on November 11 the federal government presented a new fiscal adjustment proposal (PLP 299/2026).
PLP 299/2026 does not address the cause of public indebtedness, it reduces investment and jeopardizes development.
The fiscal adjustment proposal goes beyond spending cuts: it is a significant change to the fiscal framework (Complementary Law No. 200/2023) that worsens the mechanisms restricting public investment. The country must overcome this model. The proposal was approved in the Senate the day after it was presented and is already moving through the Chamber of Deputies. An issue of this magnitude should have been discussed with society.
Beyond failing to address high interest rates — the real problem of the public accounts — this PLP also fails to create the foundations for investment to reach and surpass 20% of GDP, a crucial measure defended by President Lula in a recent statement. Its content preserves the constitutional floors for Health and Education and the link between the pension floor and the BPC (Continuous Cash Benefit) and the minimum wage. However, the adjustment does not create a lasting solution that protects these achievements, and it maintains the exhausted model of pressure for spending cuts and compression of public investment. Changing it is an indispensable condition for the continuity of the progressive project.
PLP 299/2026 introduces two structural changes. The first reduces the government’s room for maneuver in the face of revenue fluctuations. Today, the primary result target of the LDO (Budget Guidelines Law) (0.5% of GDP in 2027) allows a tolerance of 0.25% either way, and spending containment occurs only if the bimonthly primary result forecast falls below the lower bound of that margin. The proposal, however, allows spending to be frozen (contingenciamento) whenever the forecast falls below the center of the target, creating a bias toward more freezes. As a result, when the economy grows less and collects less revenue, the government — instead of expanding spending to stimulate growth and protect income and employment — may deepen slower growth by withdrawing resources from circulation.
The second change reduces the ceiling for spending growth above inflation from 2.5% to 2% of GDP whenever the spending containments provided for by the first change occur. As these become far more likely, so does the reduction of the ceiling to 2%, which harms economic growth and the well-being of the population. Equally relevant, the already very low investment by the federal government tends to suffer even greater cuts, and the minimum guarantee of real growth in social spending and public investment achieved under the framework would be partially reversed. Complying with the framework becomes even more difficult, increasing pressure from the financial market for further cuts in social rights and for keeping the Selic rate very high.
Three other changes alter the way resources in strategic areas are calculated and used. Regarding the National Fund for Scientific and Technological Development (FNDCT), the bill allows part of the resources to be allocated to study and research scholarships in higher education. The fund stops financing only projects and begins to cover running costs, which should be guaranteed without compromising it. In Health, the floor of 15% of Net Current Revenue (RCL) is maintained, but revenue from the tax on crude oil exports is excluded from the calculation base until 2030, which makes the floor grow less. The justification is that this revenue is extraordinary because of the US war against Iran and should not sustain permanent expenditures. It would be better, however, to link it to health investments, which are not permanent expenditures, such as equipping hospitals.
The third change concerns public investment. The bill allows it to be expanded in the following years, but in a fragile way and dependent on prior cuts. If there is a spending freeze during the fiscal year and the primary result at the end is above the lower bound of the tolerance margin, part of the surplus may go to “structuring investments,” but only up to the limit of the primary result target. In other words, there is no real guarantee of more investment, and overall the effect is one of investment containment. Public investment thus remains hostage to unnecessarily restrictive fiscal conditions. This is the opposite of what is needed to achieve the target of more than 20% of GDP in investment defended by President Lula.
Brazil and Its People Need Another Path
We propose another path. In social spending, a rule for spending growth adjusted to different spending profiles, taking into account, for example, demographic change and not threatening the constitutional rights that reduce inequality. The fiscal rule must be compatible with the Health and Education floors and with the growth of Social Security spending. On investment, the current rule provides for growth above inflation of at least 0.6% of GDP per year (about R$ 89 billion in 2027), but during budget execution it is subject to the overall ceiling (maximum of 2.5% of GDP, which may become 2%) and to the primary result target (0.5% of GDP in the 2027 PLOA). Thus, effective investment can fall below that floor if discretionary spending has to be cut. And that is what has happened in practice.
Since 2015, the federal government’s net investment has been negative. The framework did not change this picture, and this must change urgently. Investment by states and municipalities (which are not subject to the framework) has recovered considerably, but federal government investment remains at its lowest levels since the spending cap. Between 2010 and 2014, the period of highest gross federal investment, the percentage stood at around 0.8% of GDP; in 2024, it was only 0.24%. It is inconceivable that investment should be treated under the same rule as operating expenses. The rule must change so that public investment grows enough for the economy to return to growing 4% to 5% per year.
We Propose a New Rule for Investment within the Fiscal Framework
- The floor for federal government investment (excluding state-owned companies and transfers to states and municipalities) must grow by at least 0.2% of GDP per year until it reaches 1% of GDP in four years;
- The floor shall be mandatory in budget execution and not only in the initial forecast. To this end, federal investment must automatically fall outside the general rules (the primary result target and the spending growth ceiling), without the need to cut other discretionary spending.
The Central Problem Is the High Interest Rate
To control public debt as a proportion of GDP, the Selic rate must be reduced — the main source of growth in the debt-to-GDP ratio — and not primary spending. According to the Central Bank, in the twelve months to September 2026, the nominal deficit of the public sector was R$ 1.27 trillion: 95% (R$ 1.2 trillion) is debt interest and only 5% (R$ 70 billion) is primary spending in excess of primary revenue. Moreover, each percentage point less in the Selic reduces the growth of net debt by R$ 71 billion — the same amount as the primary deficit. The conclusion is as follows: 1) the high Selic rate is the main cause of debt growth; 2) cutting more primary spending in order to pay interest merely transfers public resources to the richest. This harms the majority of the population, increases income concentration and does not change the trajectory of the debt. The review of expenditures should focus on revenue waivers that do not contribute to productive development, and the fight against tax evasion must persist, since it still exceeds one hundred billion reais.
We Propose the Following Short-Term Measures
- Raise the center of the inflation target to 4.5% and the compliance band to 2%.
- Extend the period for assessing compliance with the target from 12 to 24 months.
- Adopt rules to reduce exchange-rate volatility in response to changes in the Selic: a) an unremunerated reserve requirement on part of the capital entering the country, discouraging short-term inflows, especially for carry trade; b) taxation of private foreign borrowings, especially by banks, at a rate that is higher the shorter the term.
As a synthesis goal of a national development project that must be built immediately, and in which these changes will serve as a lever, we propose a target of raising the investment rate to a floor of 20% (GFCF/GDP) within four years, including a target of 4% of GDP in infrastructure (today around 2.2%), the level needed to grow without bottlenecks. The investment target converges government effort and gives predictability to the private sector, placing at the center of the agenda the growth with productive transformation that the country urgently needs. We are living at the limit of a dynamic that combines cyclical fiscal adjustments with expanded social programs and a real increase in the minimum wage, yet is increasingly under pressure.
The fourth Lula government, anointed by the streets and social networks, faces the historic challenge of overcoming the model that has prevented reindustrialization, development and the construction of a sovereign Brazil on solid foundations. The communists will strive, together with the other patriotic and popular forces, so that the structural reforms advance — among them the reform of the Financial System — so that the country may face and overcome the impositions of financial capital and rentierism.
On to the Struggle!
National Executive Committee of the Communist Party of Brazil (PCdoB)